How a Credit Union Personal Loan Beats a Traditional Bank Offer
The advertised rate is only part of a loan's cost. See how credit union personal loans differ from bank offers on fees, approval, repayment flexibility, and total repaid.
Borrowers often compare interest rates first, yet the advertised number tells only part of a loan's cost. A credit union evaluates an application through membership-based lending practices, personal service, and repayment details that banks may handle differently. That difference can affect fees, flexibility, approval, and the total amount repaid. A careful comparison helps a borrower judge the complete offer before signing documents. The following points explain how a credit union loan can provide an advantage.
A personal loan usually provides a fixed amount for a defined purpose, such as debt consolidation, home repairs, or an unexpected expense. The borrower repays principal and interest through scheduled installments, while the lender reviews income, credit history, existing debts, and loan term. Learning how personal loans from a credit union are different from traditional bank offers helps reveal how those factors shape the final cost and payment.
Compare the Complete Cost
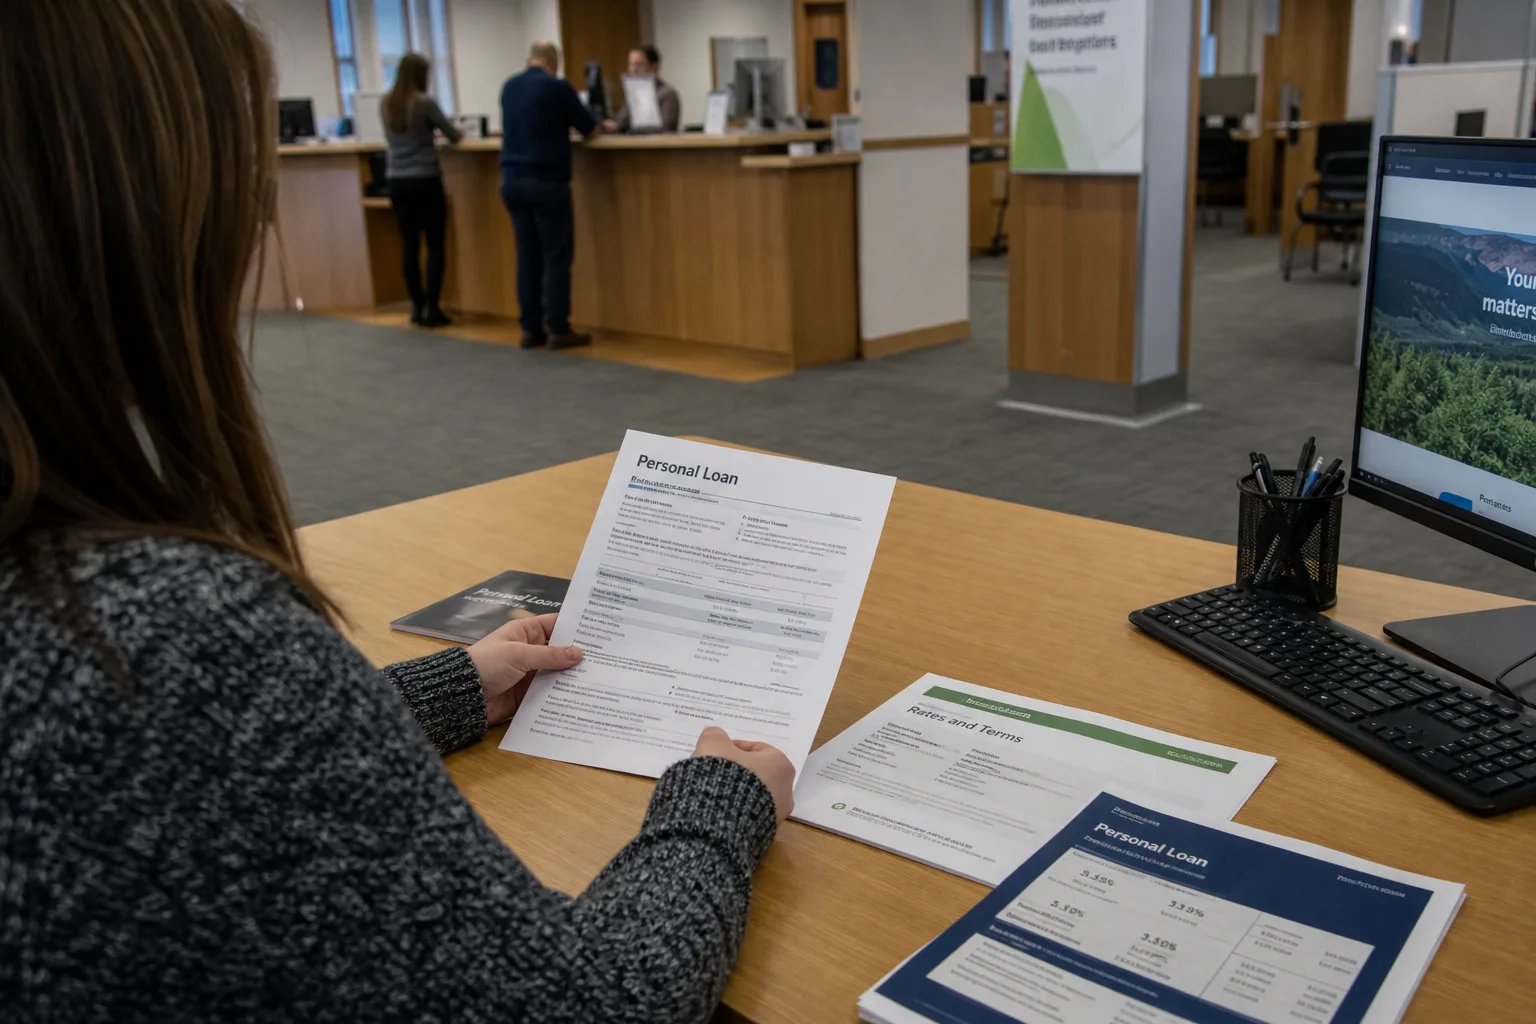
A bank advertisement may emphasize an annual percentage rate, but that number does not capture every charge. An offer can include an origination fee, late fee, or optional payment protection, depending on the agreement. The borrower should compare the annual percentage rate, finance charge, monthly payment, repayment period, and total payments. These figures show whether a lower payment results from a longer term.
Credit unions return earnings to members through pricing and service, though each institution sets its own terms. A comparison should use actual disclosures rather than assumptions. The Truth in Lending disclosure lists borrowing costs, while the loan agreement identifies payment dates, fees, collateral requirements, and early-payoff conditions.
Examine Membership-Based Service
A credit union typically serves members who meet eligibility rules, such as a connection to an employer, community, family, or association. Membership creates a direct relationship and gives the borrower a place to ask questions before accepting a loan. That access clarifies underwriting standards, required documents, and payment options.
Assess Approval With Context
Credit scoring matters for credit unions and banks, yet an application includes more than a score. Lenders review income stability, debt obligations, credit history, requested amount, and repayment period. A credit union can ask for context about a temporary setback, a recent job change, or an unusual expense. Approval still depends on lender criteria.
The borrower should check minimum credit score, income documentation, debt-to-income requirements, and collateral rules before applying. Each application can create a hard inquiry, so submitting several applications without comparing criteria is inefficient. When available, a prequalification process can show possible terms without committing to a full application, but the lender's disclosure controls the final offer.
Compare Repayment Flexibility
A traditional bank may favor standardized processes, while a credit union may discuss payment dates, term length, or extra principal payments more directly. The contract controls every option, so borrowers should ask whether early payoff carries a fee, whether payments can change, and how late charges work. Clear answers protect the budget after the loan closes.
Consider Member Value Beyond Rate
A credit union loan can fit borrowers who value local decision-making, direct service, and a clear payment schedule. Those benefits matter when an application involves unusual income or a specific repayment concern. They do not replace price comparisons. The borrower should still review the note, fee schedule, privacy disclosures, and automatic-payment terms before accepting funds.
Use a Focused Application Process
Start by identifying the exact amount needed and the purpose of the borrowing. Request a written estimate that shows the annual percentage rate, finance charge, term, payment amount, and total payments. Then compare that estimate with a bank offer with the same loan amount and terms for a fair comparison. This method prevents a low payment from hiding a higher total cost.
Before submitting documents, check the credit report for incorrect accounts, confirm income figures, and gather proof of employment or benefits. Avoid borrowing more than the expense requires. A smaller principal can reduce both the payment and interest, while a realistic term supports consistent repayment. After approval, automatic payments can prevent missed due dates, as long as the account balance is monitored.
Borrowing for home repairs like roof care or planning a move when buying or selling a home are common reasons to compare loan offers. Buyers weighing a purchase can also see Washington, Utah homes for a sense of local costs.
Conclusion
A credit union personal loan earns serious consideration when its complete disclosures, service model, and repayment terms fit the borrower's finances. A good comparison matches amounts and terms, then checks the annual percentage rate, fees, total payments, membership costs, and early-payoff rules. Before applying, a borrower should review eligibility and gather accurate income records. The next step is simple: request a written estimate, compare it with the bank's offer, and choose the payment that leaves room for regular expenses.
Frequently asked questions
Are credit union personal loans cheaper than bank personal loans?
What do I need to join a credit union to get a loan?
Does applying for a personal loan hurt my credit score?
What should I compare when choosing between a credit union and a bank loan?
Can I pay off a credit union personal loan early?
Keep reading
More from the blog
Buying a Utah Home With a Protection Dog in Mind: 6 Things to Check
How to Choose Large Sliding Glass Doors for Utah Homes
How Home Renderings Help Buyers, Builders and Sellers